
SP Angel – Morning View – Thursday 26 09 19
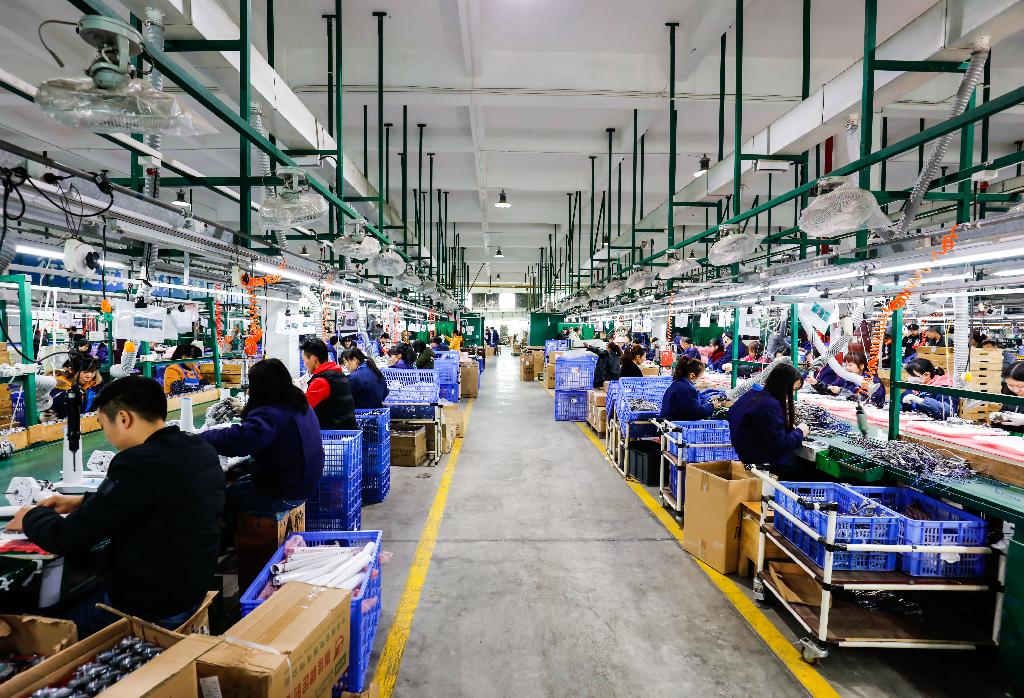
China’s factory activity contracts for fifth straight month
MiFID II exempt information – see disclaimer below
IronRidge Resources* (IRR LN) – IronRidge looks at Lihtium Hydroxide potential while drilling Ghana resource and discovering new pegmatites
Georgian Mining Corporation (GEO LN) – Government change bring new hope to Georgian shareholders for license approval
Dark Horse Resources Ltd (DHR AU) – Visible gold in Las Openas rock chips
Savannah Resources* (SAV LN) – Interim results and update on projects
Tesla – move to ‘NMC‘ lithium battery chemistry for China manufacturing of Model 3 sooner than expected
- Tesla has been using ‘NCA’ Nickel Cobalt Aluminium chemistry in its auto batteries with ‘NMC’ Nickel Manganese Cobalt oxide for its Powerwall and Powerpack stationary products.
- NMC is good for longer life cycling, eg it’s a more robust battery but NMC 811 batteries are seen as needing higher performance graphite anodes to match.
- Graphene coatings or additives to the cathode current collector should also help achieve longer 811 life.
- “LG Chem convinced Tesla to switch to NCM811 batteries based on the longer driving distances per charge. It also hinted that it may be able to begin mass producing NCMA batteries, which is even higher in nickel, beginning in 2022 to apply to EVs.”(electrek.co)
- We estimate Tesla’s cell prices must currently run at around $130-140/kWh + ~$50-60/kWh for the rest of the kit in the US with potential for costs to be lower in the new Chinese Gigafactory.
- If Tesla are moving to NMC and particularly NMC 811 then this should enable cell costs to fall further mainly due to the lower cobalt content
- Navigant Research forecast that “Lithium-ion battery cell costs could fall to as little as $76/kWh by 2030, from around $139/ kWh this year which would likely bring battery pack costs close to $100/kWh assuming pack costs also fall with rising production.
- A Tesla NMC 811 standard auto battery should contain around 11kg of cobalt costing around $400.
*SP Angel acts as UK broker to Talga Resources which is developing high performance graphite anodes for battery manufacturers.
See link for our initiation note on Talga CLICK FOR PDF
China’s factory activity contracts for fifth straight month (Reuters)
- The US-China trade war is restricting factory activity in China, leading to weak demand for manufactured products in China.
- The PMI fell to 49.5 in August according to China’s National Bureau of Statistics compared to 49.7 in July. Official PMI data is due on Monday 30th September, expected to remain flat at 49.5. PMI is below the 50-point mark which indicates that manufacturing activity is in contraction.
- Export orders fell for the 15th straight month in August and growth in China’s industrial production was at its lowest in over 17 years.
- Beijing have begun buying more US agricultural products in attempt to ease tension between the two countries. Treasury Secretary Steven Mnuchin said earlier this week that he remains hopeful that scheduled trade talks with China will go ahead in two weeks’ time. Some sort of agreement between the two nations in a fortnight is likely to improve Chinese manufacturing confidence.
|
Dow Jones Industrials |
+0.61% |
at |
26,971 | |
|
Nikkei 225 |
+0.13% |
at |
22,048 | |
|
HK Hang Seng |
+0.20% |
at |
25,997 | |
|
Shanghai Composite |
-0.89% |
at |
2,929 | |
|
FTSE 350 Mining |
+0.65% |
at |
18,154 | |
|
AIM Basic Resources |
-0.35% |
at |
2,167 |
Economics
UK – Survey shows UK consumer confidence falls to 6-year low (YouGov)
- Brexit, Trump’s trade war and more significantly severe political uncertainty is worrying consumers.
Currencies
US$1.0942/eur vs 1.1000/eur yesterday. Yen 107.69/$ vs 107.37/$. SAr 15.029/$ vs 14.921/$. $1.235/gbp vs $1.247/gbp. 0.675/aud vs 0.678/aud. CNY 7.128/$ vs 7.116/$.
US Dollar gains ground against Euro
- Dallas Federal Reserve President Robert Kalpan supported the two fed interest rate cuts earlier this year, however said that further rate cuts have "diminishing returns", a comment which strengthened the dollar.
- Sabine Lautenshläger, a member of the European Central Bank has announced that she will step down at the end of October. Lautenshläger has been against recent stimulus packages implemented within Europe. Without such a prominent figure raising concerns, the ECB may continue a policy of easing which would weaken the Euro.
- Trump’s alleged smear campaign against Democratic candidate Joe Biden by pressuring Ukrainian president Volodymir Zelensky led to uncertainty in the US markets due to the slim chances of ousting Trump. The risk- off sentiment this caused boosted the dollar.
Commodity News
Gold US$1,507/oz vs US$1,529/oz yesterday
Gold ETFs 80.9moz vs US$80.2oz yesterday
Platinum US$929/oz vs US$951/oz yesterday
Palladium US$1,648/oz vs US$1,671/oz yesterday
Silver US$17.93/oz vs US$18.53/oz yesterday
Base metals:
Copper US$ 5,778/t vs US$5,765/t yesterday
Aluminium US$ 1,748/t vs US$1,760/t yesterday - Chinese aluminium processing cut 50% to improve air quality ahead of National Day celebration (Shanghai Metals Market)
- Aluminium processing in the Henan, Tianjin, Shanxi and Shandong provinces had output restricted in order to improve air quality ahead of the Chinese National Day on the 1st of October.
- All aluminium processing in the Henan province have been closed, affecting output by around 10,000mt. The cut will have a greater effect on Shanxi and Shandong provinces, reducing output by 140,000mt and 320,000mt respectively.
- Spot prices for alumina rose 2,630 yuan ($369.18) a tonne on Wednesday, according to Reuters.
- Shanghai Metals Market expects the production cut which came into place on the 25th of September to be lifted by the 3rd of October.
Nickel US$ 17,240/t vs US$17,085/t yesterday
Zinc US$ 2,283/t vs US$2,284/t yesterday
Lead US$ 2,095/t vs US$2,069/t yesterday
Tin US$ 16,470/t vs US$16,500/t yesterday
Energy:
Oil US$62.2/bbl vs US$62.5/bbl yesterday
Natural Gas US$2.528/mmbtu vs US$2.507/mmbtu yesterday
Uranium US$25.70/lb vs US$25.70/lb yesterday
Bulk:
Iron ore 62% Fe spot (cfr Tianjin) US$87.9/t vs US$87.8/t
Chinese steel rebar 25mm US$562.0/t vs US$562.1/t
Thermal coal (1st year forward cif ARA) US$66.8/t vs US$67.7/t
Coking coal futures Dalian Exchange US$185.6/t vs US$185.9/t
Other:
Cobalt LME 3m US$37,500/t vs US$37,500/t
NdPr Rare Earth Oxide (China) US$44,964/t vs US$45,037/t
Lithium carbonate 99% (China) US$6,945/t vs US$6,956/t
Ferro Vanadium 80% FOB (China) US$38.3/kg vs US$38.3/kg
Antimony Trioxide 99.5% EU (China) US$5.1/kg vs US$5.1/kg
Battery News
VW keen to expand on its €1bn investment into homegrown battery technology (FT)
- Volkswagen opened it’s next generation battery cell manufacturing centre in Salzgitter, Germany on Monday.
- The site is home to 300 engineers looking at ways to increase cell capacity, reduce the usage of rare-earth materials and improve sustainability of production according to Motor Authority.
- VW are also pursuing more partnerships with external manufacturers having already made a deal with Swedish company Northvolt, who plan to build a major battery plant by 2023 in Salzgitter at a cost of €900m .
- This development is an attempt to compete with Tesla and Asian battery suppliers by developing their own batteries- something which most other carmarkers are not doing.
- Stefan Sommer, the group’s supervisory board member for procurement, said Volkswagen would be “sharing the risks and sharing the costs” with suppliers, but emphasised that the carmaker has no exclusive contract with any of its current partners.
Company News
IronRidge Resources* (IRR LN) 15.1p, Mkt cap £47 – IronRidge looks at Lihtium Hydroxide potential while drilling Ghana resource and discovering new pegmatites
SEE LINK FOR IRONRIDGE RESOURCES PDF NOTE
- IronRidge’s Cape Coast Lithium project continues to advance with over 8,000m of RC drilling to date. Assay grades and intersection results are expected soon.
- The program is to drill 13,200m in this third phase to confirm lithium in spodumene resources at Ewoyaa North, Ewoyaa North-East and Abonko.
- The geological team have discovered another large spodumene outcrop at Kaampakrom just 1km north the main discovery at Ewoyaa
- Kaampakrom has a potential 500m strike length and is being trenched to determine its surface extent with drilling set to start shortly.
- Another pegmatite discovery at Ndasiman is 10km to the west of Ewoyaa
- Ewoyaa shows 700m of strike and up to 100m apparent width.
- Krofo is 3km north-west of Ewoyaa with trenching showing 400m of strike and up to 25m of apparent width
- Maiden Mineral Resource estimate is due in Q1 2020
- Lithium hydroxide; test-work is underway on IronRidge material to assess the development of lithium hydroxide at ANSTO ‘Australian Nuclear Science and Technology Organisation’
- Australian miners benefit greatly from the work done by ANSTO and CSIRO, the Commonwealth Scientific and Industrial Research Organisation which give tremendous support with innovative ideas and solutions. These are well developed and funded organisations which appear to work with industry and is a system which many other nations would do well to replicate.
- The new pegmatite discoveries at Kaampakrom, Ndasiman and Krofo have been helped by the use of IronRidge in-house Laser-Induced Breakdown Spectroscopy ('LIBS') and portable X-Ray Florescence 'pXRF' and indicate significant potential for greater spodumene resources in the area.
- Previous results include:
- A 12m wide intersection averaging 5.87g/t gold from a depth of 10m, including a 2m wide section at an average grade of 33.8g/t; and
- An 8m wide intersection averaging 1.29g/t gold from a depth of 8m, including a 2m wide section at an average grade of 3.17g/t; and
- A 1m wide intersection averaging 3.13g/t gold from a depth of 32m at the end of a hole
Conclusion: IronRidge are working fast with Geodrill to complete this drilling campaign. We look forward to the assay results and to a Mineral Resource Estimate in Q1 next year.
*SP Angel act as Nomad and broker to IronRidge Resources
Georgian Mining Corporation (GEO LN) 1.2p, Mkt Cap £1.6m – Government change bring new hope to Georgian shareholders for license approval
- Political unrest in Georgia may help to unlock the impasse over the company’s exploration licenses in Georgia.
- Recent changes within the Georgian government have not yet unlocked the impasse but there is new hope with some investors that the situation might improve.
- The Georgian government says it is looking to increase foreign direct investment and expand the resources sector though this appears to be at odds with the government’s refusal to-date to extend Georgian’s key exploration license which is normally a simple and quick approvals process.
- Georgian Mining’s board have agreed to write-off their Directors fees owing since May 2018, with the exception of the Chief Executive who wrote off part of his fees highlighting their dedication to the company and their value to long-suffering shareholders.
- Costs have been reduced to a minimum with the joint venture partner continuing to contribute 50% to the cash costs.
- The company continues to maintain a ‘small team in country, at a low cost, with the aim of being able to commence work rapidly once the permit is issued.’
- Georgian Mining £380,000 in May through a placing to give a group cash balance of £428,848 at end June.
*SP Angel acts as Nomad and Broker to Georgian Mining.
Dark Horse Resources Ltd (DHR AU) A$0.0045c, A$10.3m – Visible gold in Las Openas rock chips
- Dark Horse Resources reports that rock chip sampling from the Presagio West breccia vein at its Las Openas project in Argentina has yielded visible gold from a zone up to 70m wide.
- Previously reported results from channel sampling at Presagio contained 0.8m at an average grade of 17.9g/t gold and 225g/t silver and 1m averaging 2.4g/t gold and 597g/t silver.
- The company has also identified an additional breccia vein in the far north of the Las Openas lease area at Zora and explains that the “large area between Zora and Presagio is yet to be investigated but the Company intends to include this area in the future work programme”. The Zora vein system has been sampled over 350m of strike length
- Maps contained within the announcement to the ASX show the Zora Zone located some 1-2km north of the 3.5km long Presagio system and showing a similar east/west strike orientation.
Conclusion: Initial early stage mapping, rock chip and channel sampling at Las Openas provides encouraging grades associated with extensive mineralised structures. We await further results with interest.
Savannah Resources* (SAV LN) 2.0p, Mkt Cap £24.7m – Interim results and update on projects
- Savannah Resources reports a loss of £1.97m for the six months to 30th June 2019 (2018 – loss £1.17m).
- Administrative expenses increased to £2.0m (2018 – 1.1m) reflecting increasing levels of activity particularly at the Mina do Barroso lithium project in Portugal where a DFS is underway and expected to be completed during Q2 2020.
- The company reports a 30th June 2019 cash balance of £3.08m and with the subsequent additional £3.76m raised during September, including support from its major shareholder, Al Marjan, is sufficiently funded for the completion of the Portuguese DFS and environmental impact studies and its other commitments.
- The company also takes the opportunity to summarise the progress of its principal projects.
- At Mina do Barroso, where the company published mineral resource estimates for the co-product quartz and felspar yesterday, expansion of the project through the “discovery and subsequent delineation of new orebodies … has meant that drilling campaigns have been extended, mine designs have needed to be reworked and pit sequencing plans revised. Our metallurgical test work programme has also been expanded.”
- As a result, of the additional work, the “delivery of the DFS is now expected to occur in Q2 2020 against our previous target of early 2019”. Extending the scope and timetable of the DFS is, in our opinion, a positive result of the company’s success in expanding the resource base through the discovery of additional mineralisation.
- The addition of a further two orebodies to the previously identified three adds to the complexity of the pit scheduling and, potentially, to the metallurgical variability of the plant feed but could also add the flexibility to optimise engineering development and financial returns and undoubtedly increases the scope of the feasibility work.
- Referring to recent weakness in lithium commodity prices, driven in part by the build-up of stockpiles and the “reduction in electric vehicle subsidies in the Chinese market” the company points to the longer term growth which have led “Market commentators such as Roskill continue to forecast that these growth projections for electric vehicles and lithium battery demand will challenge lithium suppliers, leading to a growing market deficit in refined lithium during the 2020s and a recovery in prices from next year”.
- Plans to finance Mina do Barroso are also advancing and the company confirms that “Work to date on the capital cost continues to indicate that the estimate from the Scoping Study of US$109m (excluding contingency) to US$124.6m (including contingency) remains a realistic range and management believes that this quantum of capital can be secured through a combination of project finance debt, EU/Government funding, offtake-related/partner financing and royalty financing. Hence the Group is confident that further finance for the Project will not be required from existing shareholders and the equity capital markets.”
- In Mozambique, the award of Mining Leases for two of the three licence applications submitted in 2018, and reports that the third is in the final stages of the process advances the Mutamba mineral sands joint venture with Rio Tinto where Savannah Resources stands to increase its interest from 20% to 35% for completing a pre-feasibility study.
- Savannah Resources presents a positive outlook for the mineral sands market and reports that “Market commentators such as TZMI have forecast for some time that prices for the key titanium minerals, rutile and ilmenite, as well as for the zircon contained in the sands would increase as existing inventories were consumed and not replaced at a sufficient rate in the face of demand growing in line with global GDP trends. Based on recent comments from existing mineral sands producers, these forecast market dynamics are now playing out”.
- This analysis, and expected continuing consumption growth leads the company to predict a need for new sources of supply including the development of Mutamba.
- Referring to delays in the permitting process for its Oman copper projects as the Government implemented the new Mining Law, Savannah Resources is “heartened by the advice received in August from the Public Authority for Mining in Oman ("PAM") that it intends to grant the mining licences over the Mahab 4 and Maqail South copper deposits which were applied for in 2016”.
Conclusion: Savannah Resources remains well funded to complete the feasibility work on the Mina do Barroso Lithium Project although the timetable has been extended until mid 2020 in order to expand the work to include additional deposits and optimise the development plan.
*SP Angel acts as Nomad to Savannah Resources
Analysts
John Meyer – 0203 470 0490
Simon Beardsmore – 0203 470 0484
Sergey Raevskiy – 0203 470 0474
Sales
Richard Parlons – 0203 470 0472
Abigail Wayne – 0203 470 0534
Rob Rees – 0203 470 0535
SP Angel
Prince Frederick House
35-39 Maddox Street London
W1S 2PP
*SP Angel are the No1 integrated nomad and broker by number of mining brokerage clients on AIM according to the AIM Advisers Ranking Guide (joint brokerships excluded)
+SP Angel employees may have previously held, or currently hold, shares in the companies mentioned in this note.
|
Sources of commodity prices |
|
|
Gold, Platinum, Palladium, Silver |
BGNL (Bloomberg Generic Composite rate, London) |
|
Gold ETFs, Steel |
Bloomberg |
|
Copper, Aluminium, Nickel, Zinc, Lead, Tin, Cobalt |
LME |
|
Oil Brent |
ICE |
|
Natural Gas, Uranium, Iron Ore |
NYMEX |
|
Thermal Coal |
Bloomberg OTC Composite |
|
Coking Coal |
DCE |
|
RRE |
Steelhome |
|
Lithium Carbonate, Ferro Vanadium, Antimony |
Asian Metal |
|
Tungsten |
Metal Bulletin |
DISCLAIMER
This note is a marketing communication and comprises non-independent research. This means it has not been prepared in accordance with the legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination.
This note is intended only for distribution to Professional Clients and Eligible Counterparties as defined under the rules of the Financial Conduct Authority and is not directed at Retail Clients.
This note is confidential and is being supplied to you solely for your information and may not be reproduced, redistributed or passed on, directly or indirectly, to any other person or published in whole or in part, for any purpose.
This note has been issued by SP Angel Corporate Finance LLP (‘SPA’) to promote its investment services. Neither the information nor the opinions expressed herein constitutes, or is to be construed as, an offer or invitation or other solicitation or recommendation to buy or sell investments. The information contained herein is based on sources which we believe to be reliable, but we do not represent that it is wholly accurate or complete. All opinions and estimates included in this report are subject to change without notice. It is not investment advice and does not take into account the investment objectives and policies, financial position or portfolio composition of any recipient. SPA is not responsible for any errors or omissions or for the results obtained from the use of such information. Where the subject of the research is a client company of SPA we may have shown a draft of the research (or parts of it) to the company prior to publication to check factual accuracy, soundness of assumptions etc.
Distribution of this note does not imply distribution of future notes covering the same issuers, companies or subject matter.
Where the investment is traded on AIM it should be noted that liquidity may be lower and price movements more volatile.
SPA, its partners, officers and/or employees may own or have positions in any investment(s) mentioned herein or related thereto and may, from time to time add to, or dispose of, any such investment(s).
SPA is registered in England and Wales with company number OC317049. The registered office address is Prince Frederick House, 35-39 Maddox Street, London W1S 2PP. SPA is authorised and regulated by the UK Financial Conduct Authority and is a Member of the London Stock Exchange plc.
MiFID II - Based on our analysis we have concluded that this note may be received free of charge by any person subject to the new MiFID II rules on research unbundling pursuant to the exemptions within Article 12(3) of the MiFID II Delegated Directive and FCA COBS Rule 2.3A.19.
A full analysis is available on our website here http://www.spangel.co.uk/legal-and-regulatory-notices.html. If you have any queries, feel free to contact our Compliance Officer, Tim Jenkins (tim.jenkins@spangel.co.uk).
SPA research ratings – Based on a time horizon of 12 months: Buy = Expected return of more than 15%, Hold = Expected return between -15% and +15%, Sell = Expected return of less than 15%