
SP Angel – Morning View – Tuesday 05 02 19
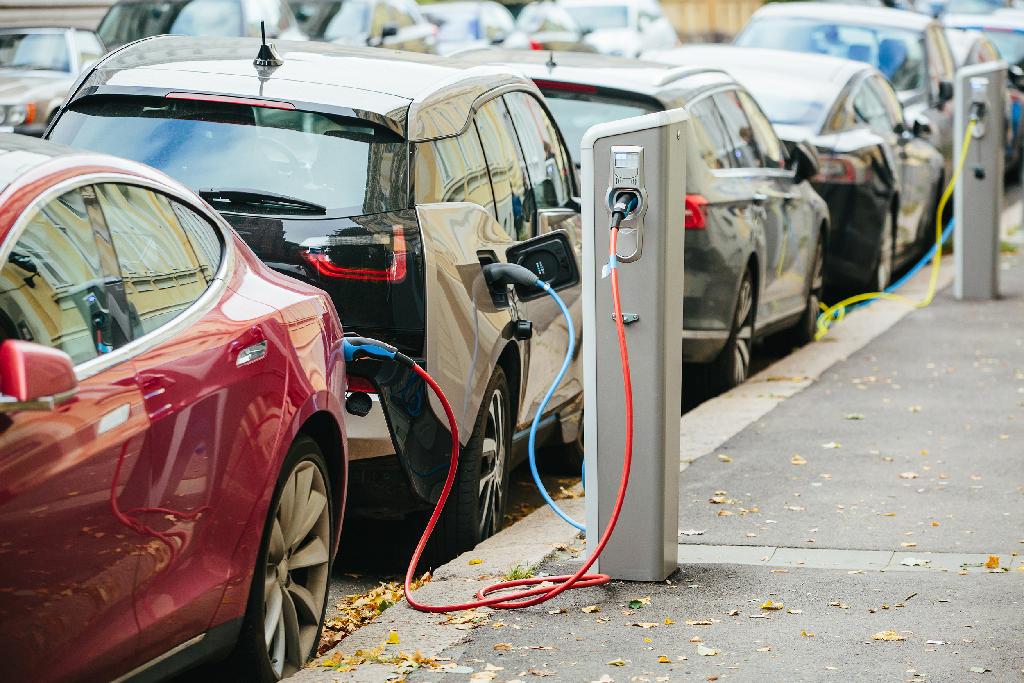
Policy paralysis stalling Australia’s EV revolution
MiFID II exempt information – see disclaimer below
BlueRock Diamonds (BRD LN) – Recovery of exceptional diamonds
Policy paralysis stalling Australia’s EV revolution
- Industry insiders and engineers continue to wonder why Australia is crawling along just past the bare minimum needed to support an expanding electric car sector. Behyad Jafari, chief executive of the Electric Vehicle Council, says the failure to so far provide this infrastructure – from charging stations and uniform standards for components, to the tools needed to maintain each vehicle – is a symptom of political paralysis that has taken hold in Canberra.
- With just 783 charging stations around the country in 2018, compared with 6,400 petrol stations, building the infrastructure to support the widespread take-up of electric vehicles is expected to draw $1.7bn funding, according to the Clean Energy Finance Corporation.
- The problem with charging infrastructure development is stemming from the infant nature of the industry and the way people will use the technology is poorly understood making it a risky investment.
- “One of the troubles for public infrastructure providers is that you invest all this money to encourage people to come to electric, but once you invest this money, people will charge at home,” director of Jetcharge and cofounder of Chargefox, Tim Washington says.
- To get around this, state and local governments have so far been eager to support the building of new charging stations, but often the support they can provide is limited by their resources and their authority.
- Help from Canberra has been slow to respond. Only last week, a key recommendation in the select committee report on electric vehicles is that the federal government needs to work with “operators in the charging infrastructure industry to develop a comprehensive plan for the rollout of a national public charging network”.
- The next challenge faced by the global industry will be growing peak-to-average demand as drivers arrive home and plug in. “The current distribution network is not designed for high peak”, according to Professor Iftekhar Ahmad from Edith Cowan University.
- “When you think about putting so much load on the network, the infrastructure lifetime can be shortened and also it can put too much stress on transformers. It has to be well planned,” he says. “It’s not currently happening in a coordinated fashion and the perspective from the government [and] the utilities is that there’s not enough cars in the market to think about it.”
- Complementing growing renewable energy capacity across Australia will take coordinated effort to upgrade charging infrastructure, drawing huge demand for electricity metals such as copper.
- The International Copper Association recognise an additional 40 million charging ports by 2027 will draw over 100,000t more copper requirement in just port charging cables, charging units and wiring to electrical panels.
|
Dow Jones Industrials |
+0.70% |
at |
25,239 | |
|
Nikkei 225 |
-0.19% |
at |
20,844 | |
|
HK Hang Seng |
+0.21% |
at |
27,990 | |
|
Shanghai Composite |
+1.30% |
at |
2,618 | |
|
FTSE 350 Mining |
+1.04% |
at |
18,953 | |
|
AIM Basic Resources |
+0.24% |
at |
2,222 |
Economics
US – factory orders unexpectedly fall in November
- New orders for U.S.-made goods unexpectedly fell in November amid sharp declines in demand for machinery and electrical equipment, government data showed on Monday.
- Factory goods orders fell 0.6%, the Commerce Department said, after an unrevised 2.1% drop in October.
UK – Brexit worries put freeze on construction
- Growth in Britain’s construction industry ebbed in January to its weakest since icy weather beset the sector last March, as uncertainty around Brexit dragged particularly on commercial building work, a business survey showed on Monday.
- The IHS Markit/CIPS UK Construction Purchasing Managers’ Index (PMI) fell to 50.6 from 52.8 in December, below all forecasts in a Reuters poll of economists that had pointed to a reading of 52.4.
- Growth in the housebuilding and civil engineering sectors slowed sharply and activity contracted in the commercial sector for the first time since March, when construction was hit by unusually cold temperatures.
- “Delays to client decision-making on new projects in response to Brexit uncertainty was cited as a key source of anxiety at the start of 2019,” Tim Moore, economist at survey compiler IHS Markit, said.
Currencies
US$1.1416/eur vs 1.1448/eur yesterday Yen 109.92/$ vs 109.83/$ SAr 13.399/$ vs 13.353/$ $1.303/gbp vs $1.309/gbp 0.725/aud vs 0.723/aud CNY 6.742/$ vs 6.742/$
Commodity News
Precious metals:
Gold US$1,313/oz vs US$1,313/oz yesterday
Gold ETFs 73.1moz vs US$73.2moz yesterday
Platinum US$822/oz vs US$821/oz yesterday
Palladium US$1,363/oz vs US$1,359/oz yesterday
Silver US$15.90/oz vs US$15.83/oz yesterday
Base metals:
Copper US$ 6,210/t vs US$6,134/t yesterday
Aluminium US$ 1,926/t vs US$1,882/t yesterday
Nickel US$ 13,240/t vs US$12,695/t yesterday
Zinc US$ 2,808/t vs US$2,787/t yesterday
- Zinc prices rise to seven-month high, supported by shortage concerns due to falling stocks and environmental constraints, while delays to new capacity across top producer China exacerbate the physical market.
- China's zinc output came in at 4.53mt in 2018, according to a survey of smelters by Antaike. That marked a fall of 4.6%, or 218,000t, from 2017, the steepest drop since 2013.
- Stocks of zinc at 112,500t are less than half the levels seen last August. Also worrying the market are cancelled warrants -- metal earmarked for delivery - at nearly 50% of total stocks.
- Concern about nearby zinc supplies has been fuelled by one company holding between 50-79% of LME zinc warrants and cash contracts.
- Zinc was the worst performer in the base metals complex in 2018, reporting a 25.7% drop on concerns of oversupply. It is up nearly 13% so far this year.
- U.S. President Donald Trump said last week he will meet Chinese President Xi Jinping soon to try to seal a comprehensive trade deal as Trump and his trade negotiator both cited substantial progress in two days of talks. Any boost in global trade is expected to tighten the zinc market as requirements rise.
Lead US$ 2,133/t vs US$2,129/t yesterday
Tin US$ 20,875/t vs US$20,860/t yesterday
Energy:
Oil US$62.6/bbl vs US$63.3/bbl yesterday
Natural Gas US$2.653/mmbtu vs US$2.705/mmbtu yesterday
Uranium US$28.95/lb vs US$28.95/lb yesterday
Bulk:
Iron ore 62% Fe spot (cfr Tianjin) US$85.8/t vs US$84.4/t
- The temporary halting of Vale SA operations at its Brucutu mine could cause an ‘incremental supply shock’ as fallout from the deadly tailings dam failure could impact production loss of about 30mt.
- The move is in compliance with a Brazilian court order issued to help improve safety after one of Vale’s tailings dam in Minas Gerais state collapsed in late January, killing more than 130 people and leveling part of a town. The output cut is on top of the planned 40mt curbs that the company will implement as it decommissions dams similar to the one involved in the fatal accident.
- The market has already been jolted by the earlier announced output cuts. Iron ore prices have climbed since Jan. 25, when the Vale dam broke, on speculation the world’s largest miner of the steelmaking ingredient could face stricter regulations, crimping supply. Futures in Singapore rose 4% in thin trading on Tuesday, after a 14% surge last week.
- Vale are appealing the additional claim, with one of the dams mentioned in the decision representing a different type than the failed tailings.
- Failure of an appeal could limit global growth, with Barclays Plc earlier forecasting 2019 growth around 34mt.
- Data reports inventories of iron ore from Brazil shipped to ports in China fell last week for the first time since November.
- Vale are expected to produce 400mt iron ore this year, with the company announcing it would aim to partially offset the 40mt lost production by increasing output across other operations.
Chinese steel rebar 25mm US$597.1/t vs US$597.1/t
Thermal coal (1st year forward cif ARA) US$81.9/t vs US$81.6/t
Coking coal futures Dalian Exchange US$196.2/t vs US$196.2/t
Other:
Cobalt LME 3m US$34,000/t vs US$34,000/t
China NdPr Rare Earth Oxide US$46,202/t vs US$46,202/t
China Lithium carbonate 99% US$10,012/t vs US$10,012/t
China Ferro Vanadium 80% FOB US$70.9/kg vs US$70.9/kg
China Antimony Trioxide 99.5% EU US$7.0/kg vs US$7.0/kg
Tungsten APT European US$260-270/mtu unchanged from previous week
Battery News
Tesla looks to purchase U.S. based Ultracapacitor producer Maxwell
- Tesla has put in an offer to buy California based Maxwell Technologies for $4.75 per share (vs. $3.07 close price pre offer) – this equates to a value of $218m.
- Maxwell, established for 50 years, has a core business developing and selling ultracapacitors. It is a top 10 producer. The Maxwell board has agreed to the deal.
- The company is also developing “dry electrode” technology for batteries.
- Capacitors store electrical charge – the amount is dependent upon the voltage applied across their plates and capacitance (measured in Farads).
- Whilst in most electronics use capacitors measured in micro farads (millionths of a farad), electric vehicles need to handle a lot of electric charge. This requires ultracapacitors that can support values ranging from milifarads to, in the case of Maxell’s technology, 2,000 Farads.
- Ultracapacitors are used for energy storage and power delivery solutions for automotive, heavy transportation, renewable energy, backup power, wireless communications and consumer and industrial electronics.
- The company has seen real success selling to China bus and tram producers
- Maxwell’s dry battery electrode targets increasing the energy density of EV batteries and its technology has already been demonstrated to achieve 300 Wh/kg. This exceeds the 250 Wh/kg (source: MIT Technology Review Dec. 2018) achieved by high-end batteries today.
- Maxwell’s technology portfolio and ability to deliver volume is clearly attractive to Tesla.
New Battery Cell Patented By Tesla
- Coming from the Tesla battery research group, this patent promises an incremental step in improving the current Li-Ion batteries.
- The research group led by Jeff Dahn were able to prove that using several additives to Li-ion batteries can improve the battery performance, lifetime expectancy, but also, cut the production costs associated with Li-ion battery cells as well.
- The patent outlines how the new two-additive mixtures in an electrolyte solvent can be used with lithium nickel manganese cobalt compounds, which is also known as an NMC battery chemistry.
Electric car charging solution could make it easier and cheaper to own one
- A new technology which will see charge points added to kerbs in Britain could make motorist’s transition to alternatively fuelled vehicles easier.
- Connected Kerb and Southwark council have teamed up to bring the points to fruition. The kerbside charging points are embedded discreetly into the kerb to provide an additional charge.
- These vehicles also act as internet connectivity points and can provide environmental, weather and traffic monitoring data for public authorities.
Model predicts lithium-ion batteries most competitive for storage applications by 2030
- Researchers at Imperial College London have developed a model to determine the lifetime costs of 9 electricity storage technologies for 12 different applications between 2015 and 2050.
- The model, which incorporates data from more than 30 peer-reviewed studies, shows that at present, the cheapest energy storage mechanism is pumped-storage hydroelectricity, where water is pumped to a higher elevation with spare energy, then released to harvest the energy when needed.
- However, as time progresses, pumped-storage hydroelectricity costs do not decrease, whereas lithium-ion battery costs come down, making them the cheapest option for most applications from 2030.
Company News
BlueRock Diamonds* (BRD LN) 0.4p, Mkt Cap £1.6m – Recovery of exceptional diamonds
- The recovery of an exceptional 8.97 carat diamond from the Kareevlei Diamond Mine in the Kimberley region of South Africa represents the third stone independently valued in excess of $50,000.
- BlueRock has previously recorded two stones; 7.76 carat stone recovered in 2017 and sold for $10,070/carat and a 10.58 carat stone recovered in 2018 and sold for $7,047/carat.
- CEO Adam Waugh adds the stone was recovered “along with two other high-quality 6.36 carat and 3.64 carat diamonds”.
*SP Angel acts as Nomad & Broker to BlueRock Diamonds
Analysts
John Meyer – 0203 470 0490
Simon Beardsmore – 0203 470 0484
Sergey Raevskiy – 0203 470 0474
Phil Smith (Technology) – 0203 470 0475
Zac Phillips (Oil & Gas) – 0203 470 0481
Sales
Richard Parlons – 0203 470 0472
Jonathan Williams – 0203 470 0471
SP Angel
Prince Frederick House
35-39 Maddox Street London
W1S 2PP
*SP Angel are the No1 integrated nomad and broker by number of mining brokerage clients on AIM according to the AIM Advisers Ranking Guide (joint brokerships excluded)
+SP Angel employees may have previously held, or currently hold, shares in the companies mentioned in this note.
DISCLAIMER
This note has been issued by SP Angel Corporate Finance LLP (“SP Angel”) in order to promote its investment services.
This information is a marketing communication for the purpose of the European Markets in Financial Instruments Directive (MiFID) and FCA’s Rules. It has not been prepared in accordance with the legal requirements designed to promote the independence or objectivity of investment research.
This document is not based upon detailed analysis by SP Angel of any market; issuer or security named herein and does not constitute a formal research recommendation, either expressly or otherwise.
The value of investments contained herein may go up or down. Where investment is made in currencies other than the base currency of the investment, movements in exchange rates will have an effect on the value, either favourable or unfavourable. Securities issued in emerging markets are typically subject to greater volatility and risk of loss.
This note is confidential and is being supplied to you solely for your information and may not be reproduced, redistributed or passed on, directly or indirectly, to any other person or published in whole or in part, for any purpose.
Neither the information nor the opinions expressed herein constitutes, or is to be construed as, an offer or invitation or other solicitation or recommendation to buy or sell investments. This information is for the sole use of Eligible Counterparties and Professional Customers only and is not intended for Retail Clients, as defined by the rules of the Financial Conduct Authority (“FCA”) and subject to SP Angel’s Terms of Business as published or communicated to clients from time to time.
It is not investment advice and does not take into account the investment objectives and policies, financial position or portfolio composition of any recipient. This document should not to be relied upon as authoritative or taken in substitution for the exercise of you own commercial judgment. SP Angel is not responsible for any errors, omissions or for the results obtained from the use of the information in this document.
This document has been prepared on the basis of economic data, trading patterns, actual market news and events, and is only valid on the date of publication. SP Angel does not make any guarantee, representation or warranty, (either expressly or implied), as to the factual accuracy, completeness, or sufficiency of information contained herein. This document has been prepared by the author based upon information sources believed to be reliable and prepared in good faith.
SP Angel, its partners, officers and or employees may own or have positions in any investment(s) mentioned herein or related thereto and may, from time to time add to, or dispose of, any such investment(s).
SP Angel Corporate Finance LLP is a company registered in England and Wales with company number OC317049 and whose registered office address is Prince Frederick House, 35-39 Maddox Street, London W1S 2PP. SP Angel Corporate Finance LLP is authorised and regulated by the Financial Conduct Authority whose address is 25, The North Colonnade, Canary Wharf, London E14 5HS and is a Member of the London Stock Exchange plc.