
Yesterday's update from satellite group Inmarsat perhaps explains why the UK group rejected an offer from US rival Echostar, but at the same time explains why it may have been a mistake. The good news is that aviation broadband has boosted Q4 earnings by nearly 15%, but this was marred by impairment charges. The latter mean that annual profits were down on the previous year, something which gives the UK company's progression something of a three steps forward / two steps back feel. Indeed, this is exactly the type of situation which makes a company vulnerable to a takeover, if only on the basis that synergies with a sector counterpart would save costs.
In the case of failed suitor Echostar the US footprint would have given the enlarged entity just the right international footprint. Considering that last summer's rejected offer was some £2 a share higher than where Inmarsat shares are now, even after the latest 6% rise for the shares today, the management of the UK company will really have to be firing on all cylinders not for shareholders to feel that it would have been an easier ride if Echostar had been given the nod last year.
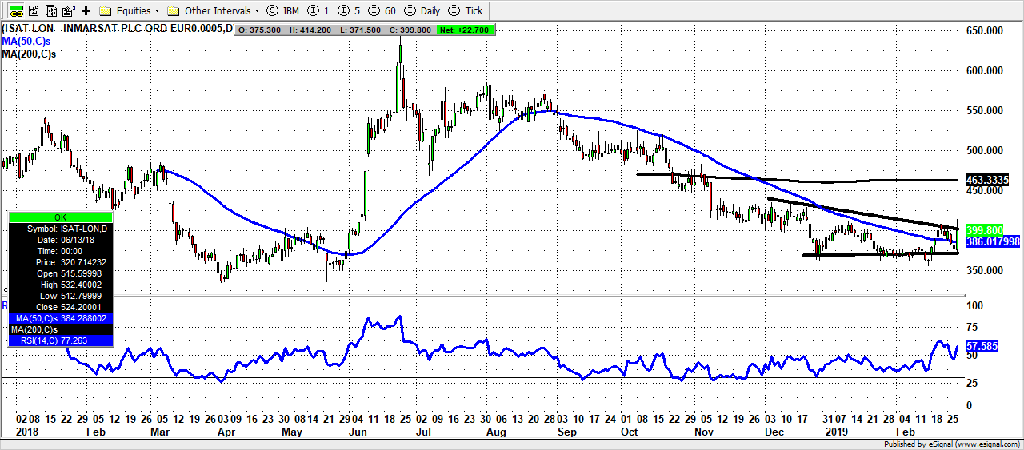
From a technical perspective it would appear that Inmarsat shares have now multi-tested a December line of resistance at 400p as new support, and they should head towards the 200 day moving average at 464p, even without further bid speculation coming out of the woodwork.