
SP Angel – Morning View – Monday 17 09 18
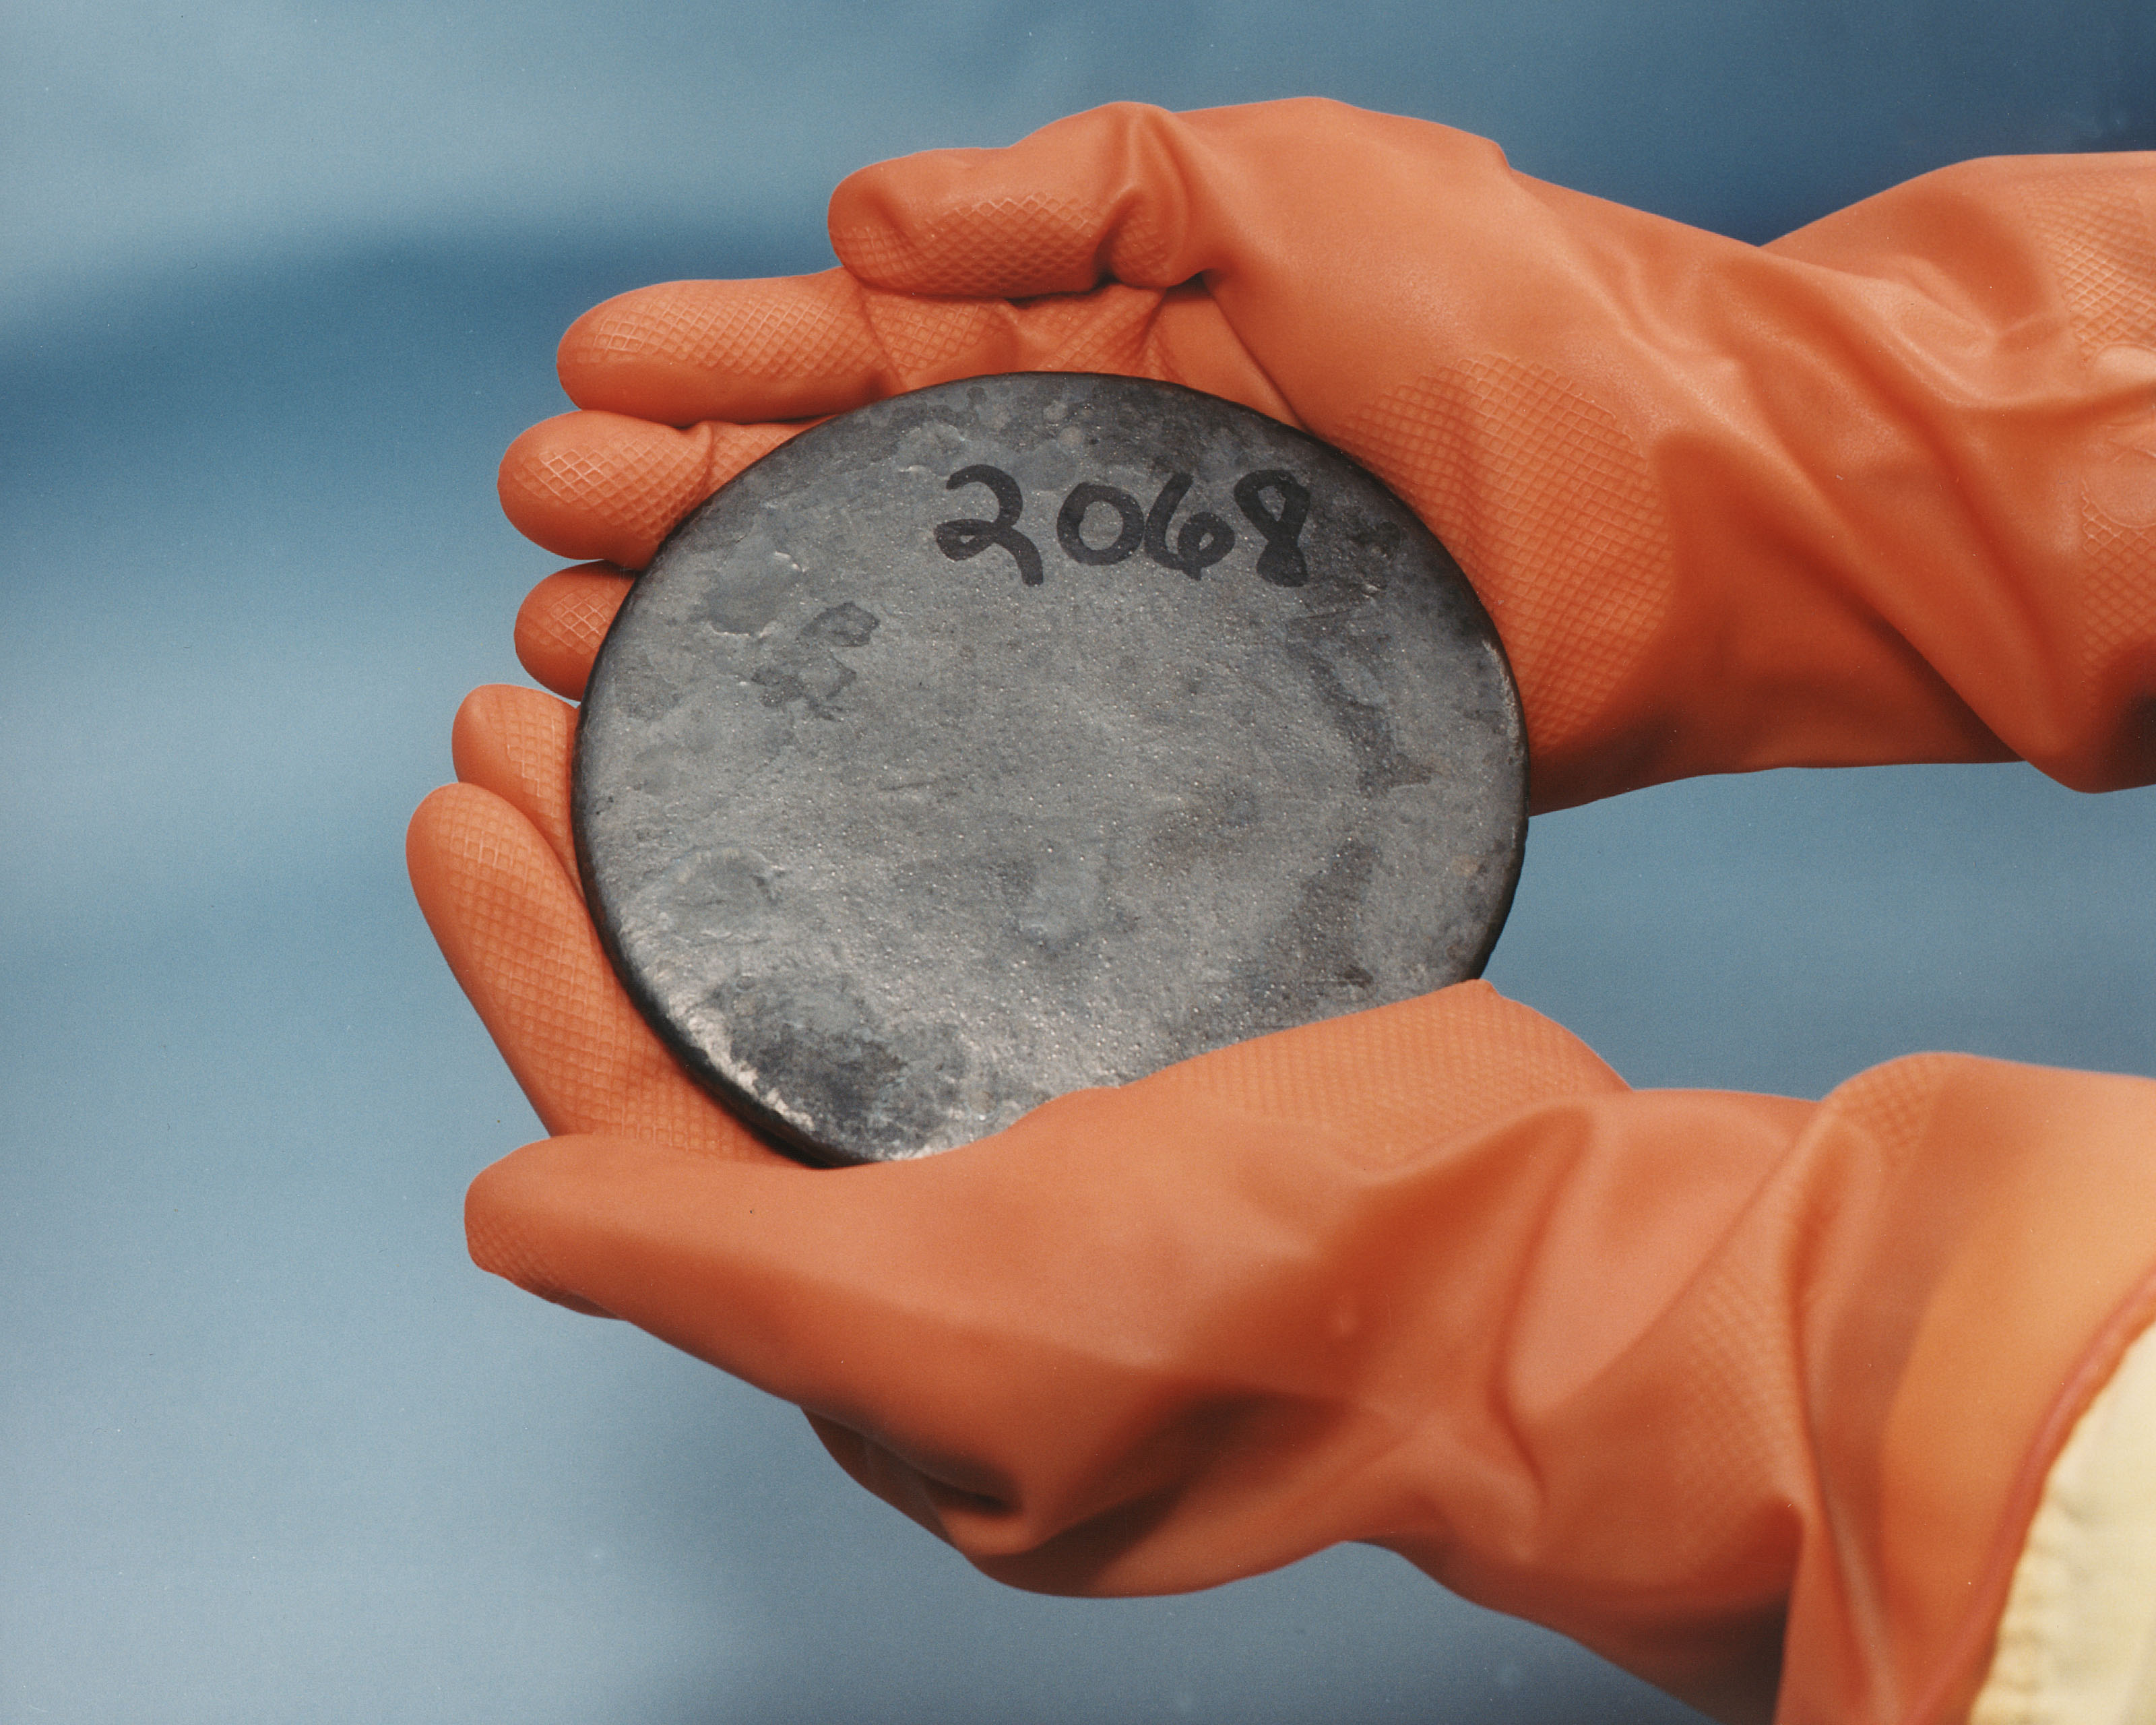
Uranium nuclear fuel rides longest run in record history
MiFID II exempt information – see disclaimer below
SP Angel are the No. 1 broker for AIM mining stocks in London
Anglo Asian Mining* (AAZ LN) – Latest update highlights significant exploration upside potential
Cora Gold* (CORA LN) – Tekeledougou exploration update
Greatland Gold (GGP LN) – Next phase of drilling at Havieron
Petra Diamonds (PDL LN) – Annual results
Serabi Gold (SRB LN) – Extension of Sprott loan
Tri-Star Resources* (TSTR LN) – Interim Results and project update
IKEA is to target home delivery by electric vehicle in five major cities by 2020
- IKEA group said on Friday that all its home deliveries in the inner cities of Amsterdam, Los Angeles, New York, Paris and Shangahi (equating to 25% of all home deliveries) would be made by electric vehicles or through other zero-emission means by 2020.
- “For us it is crucial to grow our business in a sustainable way, which is why we’re speeding up the transition to EV in five inner city areas,” says IKEA group CEO Jesper Brodin.
Battery maker Lithium Werks to open research campus in Twente
- The Dutch battery manufacturer plans to open an R&D campus in Twente.
- The company has raised €100m for investment in the site, with local business development agency Oost NL the first mover on the project.
- The company says it anticipates completion of the first building at the Technology base campus by the end of 2019.
New emission-free, low-noise, battery-operated train is revealed
- Bombardier’s new vehicle can recharge its batteries from the overhead line while operating.
- It does not generate any exhaust and is around 50% quieter than modern diesel trains.
- The current prototype is equipped with four traction batteries and can travel route of approximately 40km.
VW in talks on self-driving car standards
- Germany’s Volkswagen is in talks with other carmakers to set common standards for self-driving vehicle technology.
- The Volkswagen Group is discussing the initiative with more than 15 potential partners, according to the report, which cited an anonymous company executive.
- Carmakers, suppliers and technology companies are already investing more than €55bn ($64bn) globally in autonomous driving.
- A Volkswagen spokesman declined to comment on the report but added: “We always look for partnerships.”
|
Dow Jones Industrials |
+0.03% |
at |
26,155 | |
|
Nikkei 225 |
+1.20% |
at |
23,095 | |
|
HK Hang Seng |
-1.30% |
at |
26,931 | |
|
Shanghai Composite |
-1.10% |
at |
2,652 | |
|
FTSE 350 Mining |
+0.93% |
at |
16,179 | |
|
AIM Basic Resources |
+0.48% |
at |
2,200 |
Economics
Currencies
US$1.1632/eur vs 1.1705/eur last week Yen 111.97/$ vs 111.88/$ SAr 15.015/$ vs 14.719/$ $1.308/gbp vs $1.312/gbp 0.716/aud vs 0.721/aud CNY 6.869/$ vs 6.852/$
Commodity News
Precious metals:
Gold US$1,196/oz vs US$1,206/oz last week
Gold ETFs 67.7moz vs US$67.7moz last week
Platinum US$794/oz vs US$809/oz last week
Palladium US$976/oz vs US$983/oz last week
Silver US$14.08/oz vs US$14.23/oz last week
Base metals:
Copper US$ 5,899/t vs US$5,987/t last week
- Industrial metals broadly plunge on concern the US-China trade war is set to worsen, with President Donald Trump prepared to hit the mainland with another round of punitive levies, dampening prospects of demand in the largest consumer. Nickel lead the retreat, falling as much as -3.2% to $12,250/t on the London Metal Exchange, with copper and aluminium following suit losing -1.4% and 1.7% respectively.
- Metals have been under pressure for months as the U.S.-led trade war fans concern that the showdown will slow growth and sap consumption, while boosting the dollar. President Trump instructed aides to proceed with tariffs on an additional $200bn in Chinese products despite his Treasury Secretary’s attempt to restart talks on Friday. That may prompt Beijing to decline the offer of negotiations, according to the Wall Street Journal.
- The public comment period for a list of tariffs on around $200bn in Chinese goods closed last week, and Trump has announced the duties could be imposed “soon”. The new round would be in addition to $50bn in Chinese good which already face 25% duties.
- Money managers are slashing bullish bets on copper, adding to headwinds for the metal as a simmering trade war clouds the outlook for demand. In the week ended Sept. 11, hedge funds and other large speculators cut their long position in futures and options for a seventh straight week, the longest slump since late 2012, Commodity Futures Trading Commission data showed Friday. The exodus brought bullish wagers to the lowest in more than two years.
Aluminium US$ 2,015/t vs US$2,049/t last week
Nickel US$ 12,315/t vs US$12,570/t last week
Zinc US$ 2,304/t vs US$2,351/t last week
Lead US$ 2,026/t vs US$2,045/t last week
Tin US$ 18,925/t vs US$19,015/t last week
Energy:
Oil US$78.3/bbl vs US$78.4/bbl last week
Natural Gas US$2.781/mmbtu vs US$2.806/mmbtu last week
- China’s war on smog will be better prepared this winter heating period, as the world’s biggest energy user aims to avoid shortages which hampered last years emissions targets. Less aggressive coal-to-gas switching, improved gas storage and a boost in imports are expected to support China avoid repeating the heating crisis seen in the past winter, according the analyst from Beijing Wood Mackenzie. Last year, infrastructure problems and fuel shortages idled factories and cut off heat to homes in the dead of winter.
- The frantic effort to ensure gas supply underscores the balancing act China’s leaders are attempting to pull off as they enact policies to boost gas use in order to reduce coal smog from urban skies. While Beijing has enjoyed some of the cleanest air in the past decade since such measures ramped up last summer, the country has become more reliant on imported gas and now risks tight supply situations during winter heating months.
- Wen Wang notes “Winter is always going to be tight, and there is always going to be some shortages in terms of industrial users. It’s probably OK for some factories to not be operating in the winter, but if people do not get heating in their homes, then that’s something else. We don’t think we’re going to see that this winter.”
- China’s top oil and gas producers have been laying the groundwork for this winter, including expanding storage capacity, raising prices and planning to keep liquefied natural gas cargoes on standby at sea to plug any gaps. They’re also linking up pipelines and LNG terminals to ensure a smoother delivery of supply to users.
- To match the growing users, with policy makers targeting 2 million household conversions, China will purchase about 52-53mt of overseas supply this year, up from 38mt last year, and double the levels of 2016.
Uranium US$27.30/lb vs US$27.20/lb last week
- Global supply cuts are effectively impacting the uranium market as the price of nuclear fuel advanced to the highest level since June 2016 on Friday, capping an 11th weekly gain.
- The price has climbed from its base in April, rising 34% consistently to record the longest run on record going back to 2007.
- BMO Capital Markets forecast average prices rising $32.5/lb in the first quarter 2019, as the bank sees a supply deficit this year for the first time in more than a decade.
Bulk:
Iron ore 62% Fe spot (cfr Tianjin) US$68.7/t vs US$68.4/t
- China’s ‘green shield’ initiatives are driving iron ore’s top grades to the highest level in a year as the nation steps up its fight against pollution, as miners including Brazil’s Vale SA surge and contrast against broad losses in other raw materials from the US-China trade war.
- Spot ore with 65% iron content has risen to $96.8/t on Friday, according to Mysteel data, the highest since September 2017. Ian Roper, head of International Business at Shangahi Metals Markets notes “Its all about the winter cuts”. Iron ore superior grades have benefited as policy makers intensify their crackdown on pollution because the curbs fan demand for better-quality ores that are cleaner and more efficient. The mainland authorities have stepped up environmental inspections of mills and local mines in recent months, and are expected to broaden steel curbs this coming winter.
- Roper added a forecast for prices to top $100, and said “mills are going to be constrained in their output but their profitability is really high, so they’re focused on productivity and minimizing emissions”. The situation in China means users will “continue to chase high grades and direct charge”, referring to significantly high grade ore which can be fed straight into furnaces.
- Rebar futures have risen as the market continues to gauge the prospect of easing winter output curbs, climbing +1.% after a week whipsawed by unofficial and conflicting signals on the severity of the upcoming winter curbs and losing -2.3%.
- Hebei province has decided to apply differentiated curbs in 10 industries, including steel and coke sectors. “Hebei province will avoid blanket curbs, which means that steelmakers still have the chance to improve environmental practices and avoid output curbs.”, Maike Futures reports.
- Further, Caixin reports the nation won’t curb capacity of steel makers that meet ultra-low emissions standards during winter heating season this year, citing a document on pollution curb plan in Beijing, Tianjin, Hebei and neighbouring regions.
Chinese steel rebar 25mm US$689.7/t vs US$691.5/t
Thermal coal (1st year forward cif ARA) US$94.5/t vs US$95.6/t
Premium hard coking coal Aus fob US$182.2/t vsUS$182.2/t
Other:
Cobalt LME 3m US$63,000/t vs US$63,000/t
Tungsten APT European US$275-290/mtu vs US$275-290/mtu
Company News
Anglo Asian Mining* (AAZ LN) 50p, Mkt Cap £57.2m – Latest update highlights significant exploration upside potential
BUY – 84p (from 77p)
- The Company released a review of exploration works completed at Gedabek and Ordubad contract areas during H1/18.
- At Gadir, exploration drilling advanced at fast pace with more than 6,400m completed ahead of the expected maiden mineral resources and reserves statement targeted for completion in H2/18.
- 8 deep surface drill holes (>460m on average) for 3,695m and some 62 underground core drill holes for 2,744m completed during the period.
- Additionally, the Company mapped more than 1,700m of underground sidewall and tunnel rooftop as part of its development and production works.
- Drilling results point to the continuation of high grade orebody in the down dip direction with a surface step out drill hole (GEGDD38) located some 170m from the main defined ore zone at Gadir returning high grade gold and silver intersections.
- Additionally, mineralisation was intersected along strike (GEGDD37) beyond what was previously interpreted as an “ore controlling fault”.
- The drill hole located around 60m west of the fault returned a wide high grade intersection at deeper levels compared to the Gadir mineralisation suggesting the structure may have been downthrown by 72m on the western side.
- These results indicate mineral resource upside potential on top of the current internal estimate of 750kt at an average grade of 4.5g/t over a 80m long Gadir mineralization zone.
- Future exploration work will test identified mineralisation extensions, the mineralisation between Gadir and Gedabek as well as the area between two Gedabek zones.
- Gadir represents a valuable ore source of high grade material blended with Gedabek and Ugur ores to sweeten the process plant feed; several drill holes are reported to have returned values in excess of 3oz/t or 93g/t.
- Selected drill holes results:
- GEGDD38: 12m at 3.15g/t from 422m including 1m at 6.97g/t and 1m at 9.41g/t;
- GEGDD37: 6m at 4.15g/t from 374m and 18m at 2.88g/t from 384m;
- At Gedabek, more than 9,200m of surface drilling was completed (3,169m of diamond core and 6,087m of RC) as part of data collection and validation for the recourses/reserves mineral statement update due in Q3/18.
- Additionally, drilling confirmed the copper mineralisation remained open both down dip and easterly along strike potentially expanding mineral inventory suitable for flotation at the Gedabek processing plant.
- Gedabek orebody down dip extension continuing beneath the open pit back wall has been intersected in the development drive running some 720m from the Gadir decline.
- Core drilling at the end of the drive located below Pit 4 returned significantly wider mineralised intersections than previously estimated (double in areas) while demonstrating good grades as well.
- In particular, one drill hole in the area (EDD1512P4-2-2) returned 35.6m at 3.1g/t.
- The plan is continue with drive development works extending the tunnel beneath the back wall that would provide further drill chambers to test the Gedabek mineralisation.
- As highlighted, above the area between the Gadir and Gedabek will be also tested as “it is currently interpreted that the mineralisation of both zones is offset by a fault structure”.
- At Ugur, exploration drilling amounted to nearly 2,300m in 5 core drill holes with only one returning good copper and silver grades but at depth (UGDD51: 8.4m at 1.15% Cu and 134g/t Ag from 302m).
- The area with other targets are planned to be tested with an airborne geophysics study planned for Q3/Q4 this year.
- At Ordubad Contract Area, exploration works included surface geological mapping and sampling in the Shekerdere area.
- Discussions are ongoing for ground based electrical geophysics, core drilling and research institute cooperation with regards to remote sensing interpretation and porphyry style mineralisation analysis.
- Gedabek tailings dam is estimated to host in excess of $30m worth of copper and gold (using $1,250/oz and $6,300/t prices) accumulated over years of operation which would be subject to an assessment for future reprocessing opportunity.
Conclusion: Extensive exploration programme yields positive results indicating significant resource expansion potential. Updated Gedabek mineral resources/reserves statement is due this month while maiden Gadir resources/reserves estimate expected in Q4/18. In addition to that, latest round of drilling as well as underground development returned wide high grade intersections pointing to mineralisation extensions at Gedabek and Gadir orebodies. In particular, step out drill holes at Gadir indicate a continuation of the orebody down dip and potentially along strike while core drilling from the underground drive beneath the Gedabek open pit returned wide high grade intersections indicating the mineralisation continues in the down dip direction. Drilling from the underground tunnel between Gadir and Gedabek showed grades of over three ounces per tonne with the area planned to be also drill tested in the future. Surface drilling at Gedabek showed that copper mineralisation remained open at depth as well as easterly along strike. As previously announced, the Company is preparing for the first airborne geophysical survey at the Gedabek contract area to identify prospective exploration targets while a team on the ground at the Ordubad license area progresses with surface mapping and geochemical sampling of the identified alteration zone assessing the area for potential to host porphyry style system.
While new JORC compliant mineral resources/reserves estimates for Gedabek and Gadir are due shortly, exploration results point to the potential to improve on those as the team drill tests highlighted prospective areas. This in turn bodes well for an extension of the life of mine.
We have updated our target valuation estimating Gedabek NPV(8%DR) and blending it with the market multiples valuation to arrive at $135m NAV or 84p per share (from 77p). We will release updated earnings estimates as well as production schedule assumptions shortly.
*SP Angel act as Nomad and broker to Anglo Asian Mining
Cora Gold* (CORA LN) 12.4p, Mkt Cap £6.8m – Tekeledougou exploration update
- The Company released the last series of assay results from exploration drilling at the Tekeledougou project in Southern Mali.
- RC drill holes results extended gold mineralisation strike to 1,100m at the Kouroudian prospect and 350m at the Woyoni target.
- At Kouroudian, a total of 15 inclined 90-120m deep drill holes were completed as part of the second phase of RC drilling to test strike extensions, continuation and distribution of gold mineralisation.
- The team has also completed a single core drill hole central to the prospect to collect data on controls and structure within the mineralised zone.
- quartz veining was encountered in all drill holes while gold mineralisation varied across assays ranging from anomalous values (>0.1g/t) over several meters through to 1-4g/t over select 1-2m intervals.
- Selected drilling results included:
- TKC0025: 1m at 4.51g/t from 15m and 1m at 10.51g/t from 28m;
- TKC0029: 1m at 3.89g/t from 41m;
- TKC0031: 1m at 24.9g/t from 83m;
- TKC0037: 1m at 2.85g/t from 27m.
- At Woyoni, 6 RC drill holes were completed with only low grade gold intersections recorded in the southern section of the target and better grades encountered to the north.
- Deeper RC drilling is reported to have been limited due to a water inflow in drill holes which in turn has been overcome by completing 4 core ‘tails’.
- In total 411m of oriented HQ core was drilled to hole lengths of 150-190m.
- Selected intersections included:
- TKC0022: 1m at 2.18g/t from 40m;
- TKC0039: 3m at 4.89g/t from 48m;
- TKD003: 3m at 2.41g/t from 85m and 1m at 3.96g/t from 109m;
Conclusion: Resutls from the latest series of drilling have not matched the first set released earlier this year with the team now evaluating all data planning the next stage in the programme at Tekeledougou. Meanwhile, drilling has been paused during the rainy season in Mali with the team planning to restart drilling programme at the Sanankoro Gold Discovery shortly.
SP Angel acts as Joint Broker to Cora Gold
Greatland Gold (GGP LN) 1.115 pence, Mkt Cap £35.8m – Next phase of drilling at Havieron
- Greatland Gold reports that it has started a second phase of drilling at its Havieron prospect in the Paterson area of Western Australia.
- The programme, which comprises up to 10 cored holes each up to 600 meters depth is intended to “further determine the extent and direction of the high-grade zone of mineralisation at Havieron that was detected in Greatland's maiden drilling campaign conducted earlier this year”.
- Results from the earlier campaign, which took place between April and May this year, included:
- An intersection of 121m at an average grade of 2.93g/t gold and 0.23% copper from a depth of 497m and included an 11.5m long section from a depth of 568.5m which averaged 21.23g/t gold and 0.67% copper in hole HAV001; and
- A 21m wide intersection at an average grade of 3.79g/t gold and 0.44% copper from a depth of 418m in hole HAD003
- The company points out that the earlier drilling “established the presence of a zone of high grade mineralisation (peak grades 137.69g/t gold and 4.11% copper) and demonstrated the potential for Havieron to represent a very large mineralised system”.
- Greatland Gold is issuing approximately 11.4m shares worth A$250,000 or £142,045.45 to its drilling contractor, DDH1 Drilling, as part payment for its services. These shares represent less than 0.4% of the enlarged capital and has an unlisted, non-transferable warrant attached entitling the holder to purchase of an additional share at a price of 2p/share.
Conclusion: The results of its initial drilling work at Havieron have encouraged Greatland Gold to start a follow-up campaign to get a clearer view of the extent and scale of the mineralisation. We await results with interest.
Petra Diamonds (PDL LN) 38.28p, Mkt Cap £331.3m – Annual results
- Petra Diamonds reports a loss of US$203.1m for the year ending 30th June 2018 (2017 – profit of US$20.7m). The result reflects a loss of US$104.3m on the discontinued operation at the KEM joint-venture as well as a previously announced US$66m impairment charge against the Koffiefontein mine.
- The company, however, highlights the 37% increase in adjusted EBITDA to US$195.4m (2017 – US$142.6m) and the 25% increase in revenue to US$495.3m (2017 US$394.8m).
- The adjusted operating cash flow rose by 7% to US$157.0m (2017 – US$147.0m) “despite the negative impact of the blocked Williamson parcel and overdue VAT receivables in Tanzania.”
- Petra Diamonds notes that, towards the end of the financial year operational improvements became apparent at Koffiefontein “as a result of the commissioning of the new ground handling system in Q3 FY 2018” and that, with these improvements continuing so far this financial year, “We believe that we have now put the right conditions in place for this mine to start making a positive contribution to the Group in the current financial year”.
- The rationalisation of the operating portfolio has seen the disposal of the KEM joint-venture to the sole ownership of Ekapa Mining “thereby ensuring its sustainable future, under the stewardship of an operator best suited to maximise its value”.
- Net debt fell to US$518.8m at 30th June 2018 (30th June 2017 – US$553.4m) with the cash component representing US$236.0m (2017 – US$203.7m).
- Commenting on the results, CEO, Johan Dippenaar, pointed out that “FY 2018 yielded good operational results, the highest on record to date, in spite of the challenges experienced in FY 2017 and H1 FY 2018, and this was underpinned by strong safety performance across the Group.”
- Petra Diamonds explained that the “diamond market was stable throughout FY 2018, though subject to normal seasonal fluctuations in pricing, with Petra's prices on a like-for-like basis were up ca. 2% for the Year, compared to FY 2017. … The start of FY 2019 saw typical seasonal weakness during Petra's first tender of the year with prices down ca. 5% on a like-for-like basis, compared with H2 FY 2018, mainly due to softer prices in smaller size ranges. The Company expects the diamond market to be broadly stable during FY 2019.”
Conclusion: Petra Diamonds has rationalised its operating portfolio with the disposal of KEM and the improvements at Koffiefontein we look forward to the fruits of the strategy in FY 2019
Serabi Gold (SRB LN) 52.5p Mkt value £30.9m – Extension of Sprott loan
- Serabi Gold reports that it has agreed an extension to the US$3m secured loan with Sprott Resource Lending Partnership which was taken out in January 2018.
- Under the revised terms, the loan maturity date has been extended until 30th June 2020 from the original date of 30th September 2018. Monthly repayments will be paid over 22 monthly instalments commenting on 30th September 2018.
- “In consideration for granting the extension, Serabi has agreed to issue to Sprott, 145,479 new ordinary shares of 10 pence each (“Ordinary Shares”) at a price of 47.25 pence per share (representing a 10% discount to the closing price on 14 September 2018), equivalent to US$90,000.”
- Commenting on the added flexibility the company gains from the extension of the loan, CEO, Mike Hodgson, pointed out that “The issue of the trial mining licences for the Coringa project which we announced during August (see news release of 20 August 2018) has provided the Company with the opportunity to access and evaluate parts of the Serra orebody from underground earlier than we had originally anticipated. This will provide a better understanding of the orebody which will be hugely beneficial in the mine planning and design. It means, however, that we will be incurring development costs earlier than we originally anticipated so extending the term of the US$3 million Loan provides the Company with the flexibility to fund this additional work.”
- In addition to the continuing support of Sprott, in April, the company announced that it had received a US$15m investment from Greenstone Resources which acquired a 29.82% interest. The financial support of two influential backers underpins Serabi Gold’s plans to increase gold production from the current 2018 guidance of 40,000oz to 100,000oz pa within two years. The development of Coringa looks to be an important element of the growth plans.
Conclusion: The extension of the loan repayment schedule reflects the priority to advance Coringa as part of Serabi Gold’s expansion plans.
Tri-Star Resources* (TSTR LN) 47p, Mkt Cap £44.2m – Interim Results and project update
(Tri-Star holds 40% of jv company SPMP alongside The Oman Investment Fund and Dutco Natural Resources)
(Odey Asset Management, holds a 72.06% interest in TriStar Resources)
- TriStar Resources has announced a loss of £1.00m for the six months ending 30th June 2018. The comparable period in 2017 reported a loss of £5.31m, which included a charge of £3.64m loss relating to extinguishing debt.
- The results also reflect a sharp reduction in administrative expenses from £0.410m to £0.285m, partially offset by £100,000 relating to restructuring of the board and management team. The company points out that “A key factor in the reduction of administrative expense was the reduction of the Board from six to four members and the restructuring of executive remuneration” and that additional “savings were realised through contract re-negotiations and replacement of some service providers” as well as the disposal of non-key assets.
- Additional cost-containment measures include a move “to a share-based compensation structure to preserve cash resources and align management more closely with shareholders”.
- Following the July 2018 placing of £13m, the company reports that “at 31 August 2018 Tri-Star held £7.25m in cash. This cash balance arises as only US$5.13m of the £14m raised in July 2018 had been invested in SPMP at the end of August 2018.”
- The company’s loans to its 40% owned SPMP have increased to £7.1m and the company points out that these loans accrue interest at 15% per annum.
- Operationally, SPMP is currently well into the commissioning of its plant at Sohar and expects to produce the “first antimony metal by the end of October and first gold shortly thereafter”.
- SPMP has also built its network of feedstock suppliers and established contracts with raw materials suppliers. Purchases of feedstock are underpinned by “a total of US$13.8m in letter of credit facilities from Bank Nizwa S.A.O.G and Alizz Islamic Bank S.A.O.G”.
- The company also highlights the appointment, as CEO of SPMP, of Steven Din who joins from Konkola after a career which includes filling senior roles with Rio Tinto in Africa. Mr. Din is currently “carrying out a full operational review using some of the most experienced experts in the field to aid in the hot commissioning and troubleshooting”.
- Commenting on the results, the Acting Chief Executive of TriStar, Karen O’Mahony stressed that “This financial report comes at an exciting time in the history of the Company with our flagship Oman project almost ready to produce first metal.”
- She also underlined the focus on cash cost reduction at the corporate level which allows “shareholders’ funds to be applied to getting this project into production. … [and on] … ” streamlining Tri-Star and its other subsidiaries to ensure that as much value as possible from the underlying asset is realised for the Company’s shareholders”
Conclusion: The imminent production of the first metal from the SPMP plant in Oman represents the culmination of a long, and at times difficult journey during which the SPMP team, now under the leadership of Steven Din, have ultimately prevailed. The cost focus at all levels of the company should come as welcome news to investors as they await confirmation of the start of production.
*SP Angel acts as Nomad and Broker to Tri-Star Resources
Analysts
John Meyer – 0203 470 0490
Simon Beardsmore – 0203 470 0484
Sergey Raevskiy – 0203 470 0474
Phil Smith (Technology) – 0203 470 0475
Zac Phillips (Oil & Gas) – 0203 470 0481
Sales
Richard Parlons – 0203 470 0472
Jonathan Williams – 0203 470 0471
SP Angel
Prince Frederick House
35-39 Maddox Street London
W1S 2PP
*SP Angel are the No1 integrated nomad and broker by number of mining brokerage clients on AIM according to the AIM Advisers Ranking Guide (joint brokerships excluded)
+SP Angel employees may have previously held, or currently hold, shares in the companies mentioned in this note.
DISCLAIMER
This note has been issued by SP Angel Corporate Finance LLP (“SP Angel”) in order to promote its investment services.
This information is a marketing communication for the purpose of the European Markets in Financial Instruments Directive (MiFID) and FCA’s Rules. It has not been prepared in accordance with the legal requirements designed to promote the independence or objectivity of investment research.
This document is not based upon detailed analysis by SP Angel of any market; issuer or security named herein and does not constitute a formal research recommendation, either expressly or otherwise.
The value of investments contained herein may go up or down. Where investment is made in currencies other than the base currency of the investment, movements in exchange rates will have an effect on the value, either favourable or unfavourable. Securities issued in emerging markets are typically subject to greater volatility and risk of loss.
This note is confidential and is being supplied to you solely for your information and may not be reproduced, redistributed or passed on, directly or indirectly, to any other person or published in whole or in part, for any purpose.
Neither the information nor the opinions expressed herein constitutes, or is to be construed as, an offer or invitation or other solicitation or recommendation to buy or sell investments. This information is for the sole use of Eligible Counterparties and Professional Customers only and is not intended for Retail Clients, as defined by the rules of the Financial Conduct Authority (“FCA”) and subject to SP Angel’s Terms of Business as published or communicated to clients from time to time.
It is not investment advice and does not take into account the investment objectives and policies, financial position or portfolio composition of any recipient. This document should not to be relied upon as authoritative or taken in substitution for the exercise of you own commercial judgment. SP Angel is not responsible for any errors, omissions or for the results obtained from the use of the information in this document.
This document has been prepared on the basis of economic data, trading patterns, actual market news and events, and is only valid on the date of publication. SP Angel does not make any guarantee, representation or warranty, (either expressly or implied), as to the factual accuracy, completeness, or sufficiency of information contained herein. This document has been prepared by the author based upon information sources believed to be reliable and prepared in good faith.
SP Angel, its partners, officers and or employees may own or have positions in any investment(s) mentioned herein or related thereto and may, from time to time add to, or dispose of, any such investment(s).
SP Angel Corporate Finance LLP is a company registered in England and Wales with company number OC317049 and whose registered office address is Prince Frederick House, 35-39 Maddox Street, London W1S 2PP. SP Angel Corporate Finance LLP is authorised and regulated by the Financial Conduct Authority whose address is 25, The North Colonnade, Canary Wharf, London E14 5HS and is a Member of the London Stock Exchange plc.