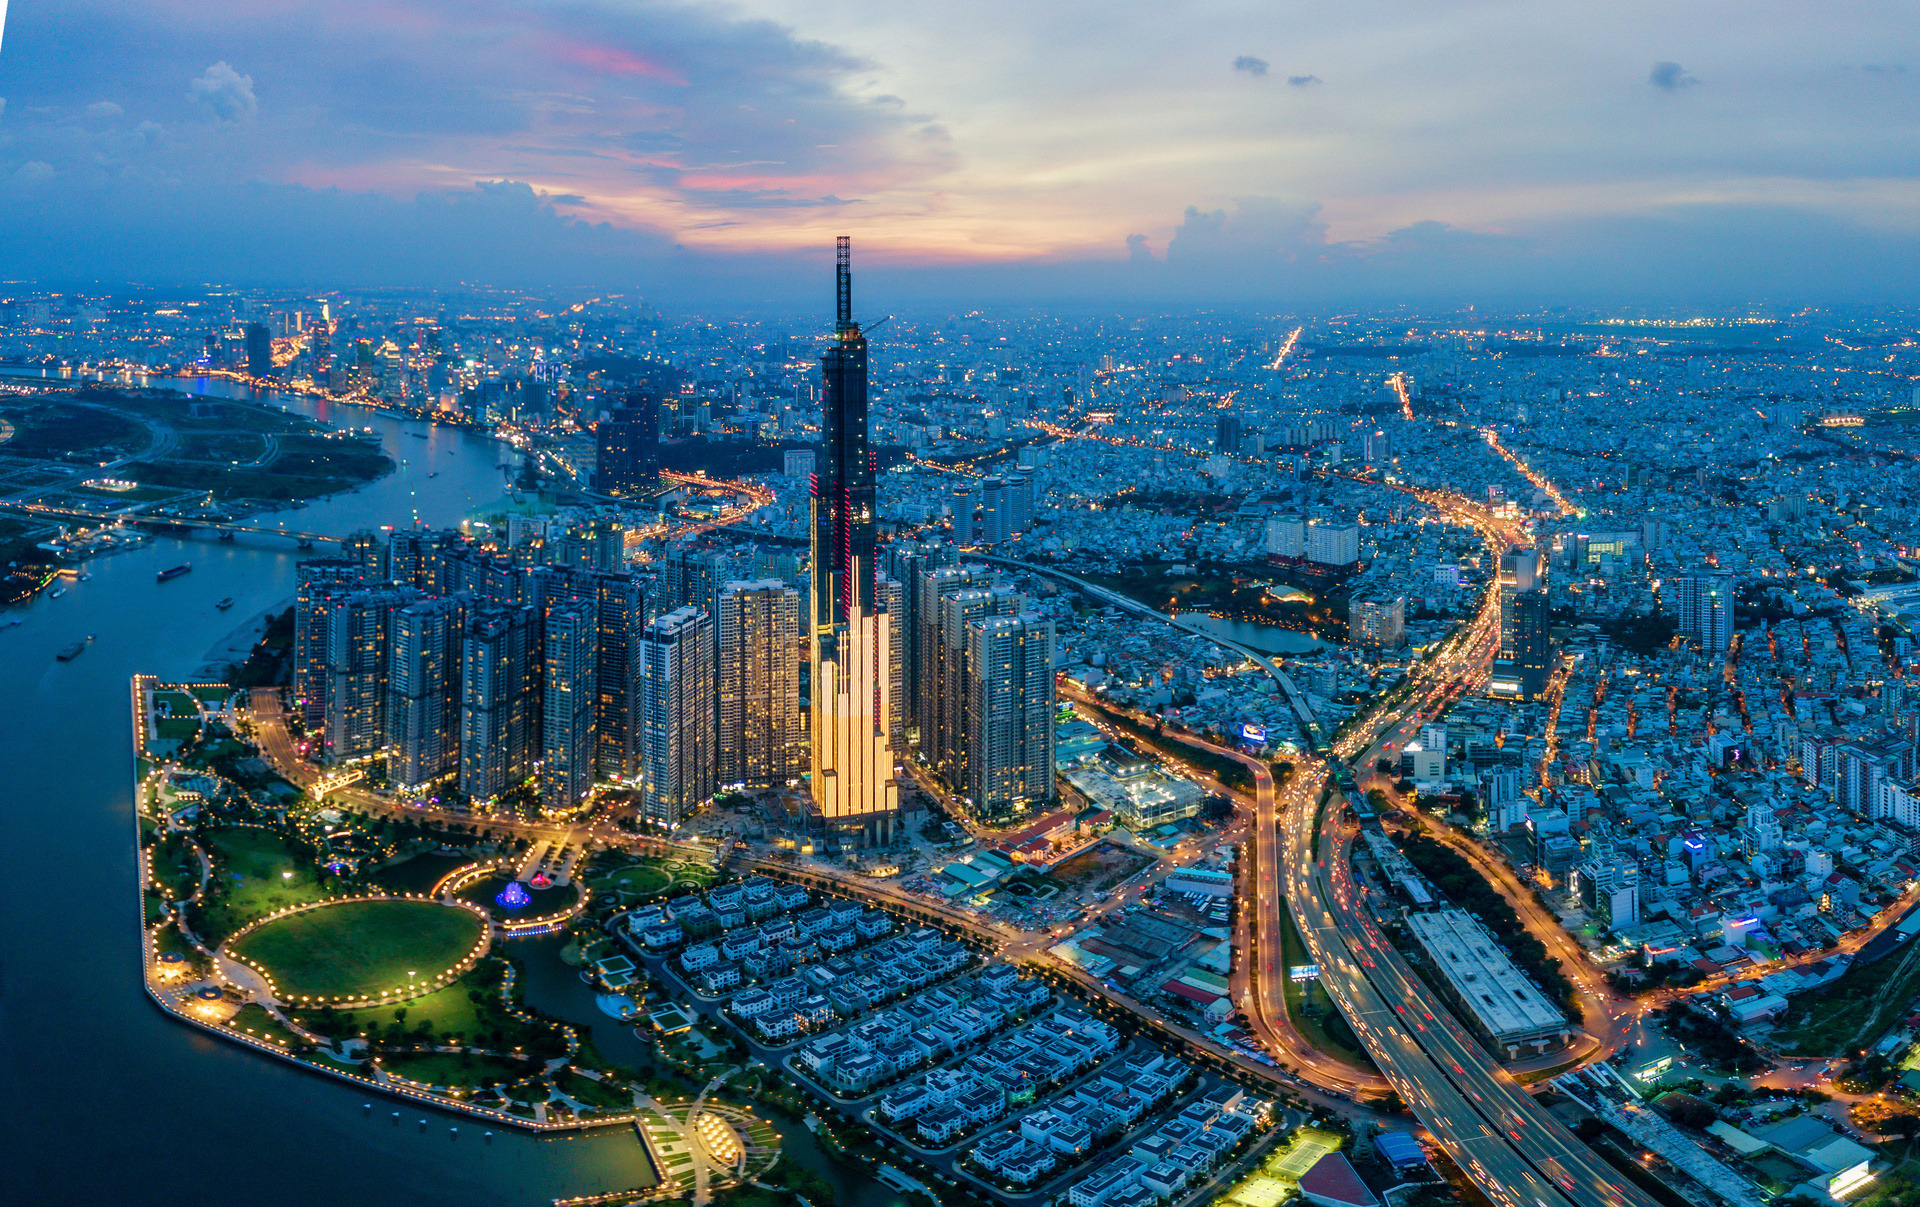
VietNam Holding (VNH) said Vietnam’s economy continued to expand strongly in September, even as the country’s equity market declined amid tighter liquidity, higher funding costs and global uncertainty.
Vietnam’s gross domestic product grew 9.95% year on year in the third quarter, putting it among the fastest growing sizeable economies globally. However, the Vietnam All Share Index fell 3.9% during September, while VNH’s net asset value declined by a smaller 2.6%.
The market weakness came despite Vietnam securing its long-awaited FTSE Russell Secondary Emerging Market upgrade. VNH said the subsequent sell-off showed the upgrade alone could not immediately overcome concerns around liquidity and funding costs, with foreign investors remaining net sellers during the month.
Exports increased 39.1% year on year in September, taking growth for the first nine months of 2026 to 24.5%, led by computers and electronics. Imports rose 36.7% over the nine-month period, reflecting increased spending on machinery, electronics and production inputs.
Vietnam recorded a US$1.27 billion trade surplus in September, although the cumulative deficit for the year stood at US$19.42 billion. Meanwhile, retail sales grew 14.1% during the month and 13.4% over the first nine months.
Public investment disbursement reached US$21.8 billion, its highest level at this point in the year for five years, as the government continued its infrastructure programme. However, VNH noted that credit growth is outpacing deposit mobilisation, increasing competition for funding across the banking sector.
Against this backdrop, the fund is becoming more selective, favouring businesses that generate their own capital, have access to lower-cost funding or can deliver strong returns on invested capital.
Its largest holding, Mobile World Group, is benefiting from stronger store sales, improving margins and economies of scale, with its Dien May Xanh consumer electronics business reporting 29% revenue growth during the first nine months. Mobile World trades at about 10 times forecast 2026 earnings, with earnings per share growth of about 18% per annum expected.
MB Bank, VNH’s second-largest holding, continues to benefit from payroll relationships, digital banking capabilities and a relatively low-cost deposit base. PetroVietnam Technical Services, meanwhile, has an estimated US$7 billion order backlog for 2026 to 2030 across energy infrastructure projects, offshore wind and overseas contracts.
The overall portfolio trades at about 10 times forecast 2026 earnings, with VNH believing considerable value remains to be recognised across its holdings.
View from Vox
Vietnam’s strong economic growth and rising investment continue to support the long-term outlook, although September showed that equity markets can diverge from underlying economic performance. VNH’s focus on companies with strong funding positions and capital discipline could prove valuable as liquidity conditions remain tighter.