As we seem to be totally obsessed with AI, or SI as President Trump would describe it, I thought I would ask Copilot to write me a summary of the UK stock market highlights of the week. By the way, given President Trump for renaming things, I am going to refer to the United States of America as “New Britain” from now on.
But as far as the AI generated update, which I am sure many of my peers now lean on, I was gratified to see that the result of the prompt was that I now know no more about what happened in the markets this week than before. There were mentions of rising gilt yields, Budget fears and the price of Crude Oil, without mentioning the “treacherous” diesel deal between the President of New Britain and President Putin. The deal makes a mockery of all the sanctions et al against Russia in recent years, but hey, Trump needs to win those midterms.
As far as the non AI highlights from the small cap area, it was all about the three m’s.
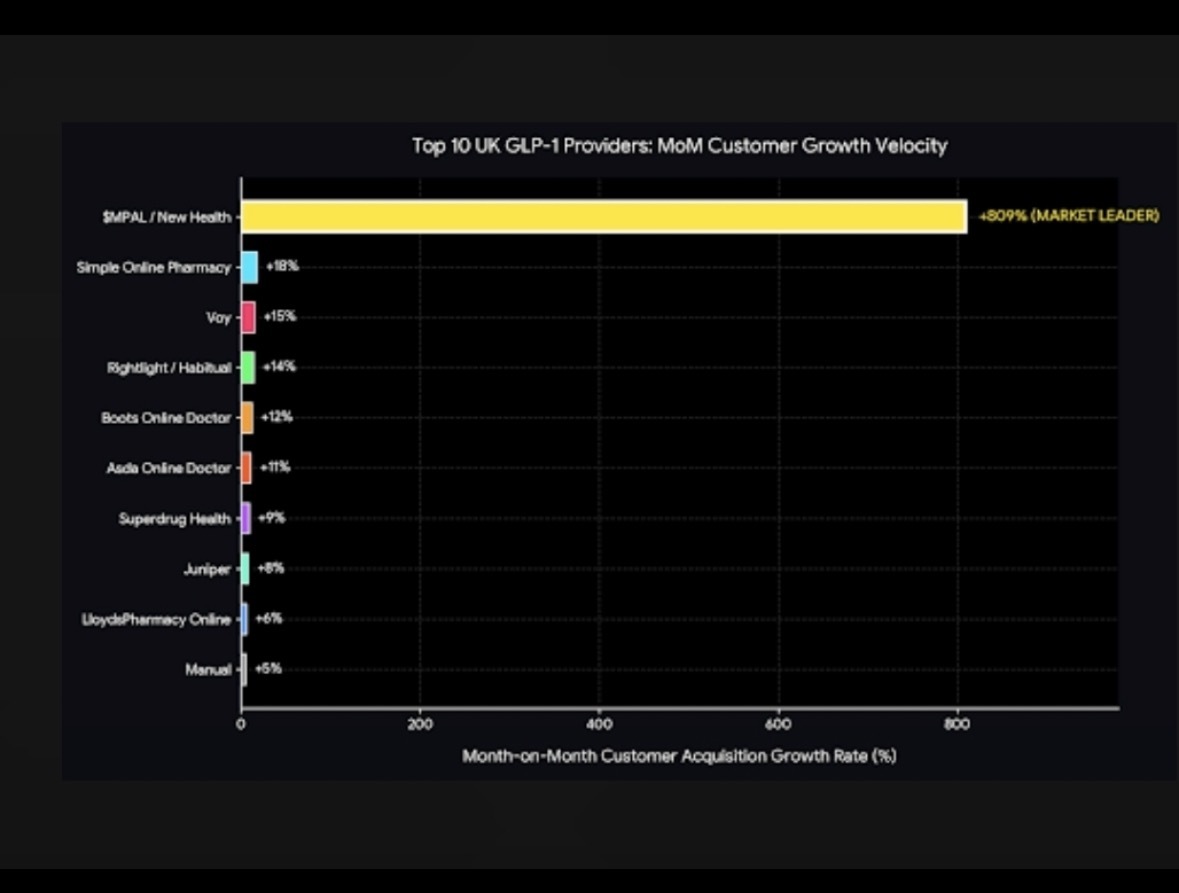
Medpal (MPAL) , MobilityOne (MBO) and Mercantile Ports (MPL) . MPAL we already know is on a roll, having seen off the competition in the GLP-1 field. With everyone and their mother apparently on weight loss jabs, it has been up to those with the greatest capacity, efficiency, and marketing savvy to win the race as far as the GLP-1 land grab.
MBO, recently back from suspension, with its interim results in, and potential cash wins and Far East growth was an obvious relief based winner. MPL was up 100% as it announced “oral submissions in rejoinder in the proceedings concerning its subsidiary i.e. Karanja Port were made before the National Company Law Tribunal on 24 September 2026.” Clearly, the market is inspired by what may happen next.
A couple of weeks ago I suggested that Huddled (HUD) could be a big mover to the upside given the charting set up of shares finding support above a rising 50 day moving average. I would venture to suggest that a 59% share price rise this week fits the bill as far as the bullish call was concerned.
Perhaps of just as much interest was the recent update from the company: “Following a series of successful trials, the Board has decided to pivot the Group to being a live commerce business, where the Board believes there is significant growth potential. Post-Period trading has been encouraging, with live commerce revenue now running at circa £100,000 per week at a product margin of circa 40%.” It would appear that there is much more to come as far as the share price upside of HUD. 1.25p versus 0.67p currently is a technical destination for perhaps as soon as the end of next month, if not the end of the year.
For almost the whole time that Georgina Energy (GEX) has been listed, and even before, it has been subject to the type of shameful, crackpot, spiteful name calling that still blights and is still countenanced by the powers that be in the market. (Details upon request regarding how this works.) But what is particularly sweet about companies and individuals who have to suffer such arbitrary / shorting based / clickbait attacks, is that when they win, all of a sudden the neigh sayers go quiet. Indeed, you know that a company is on its way when the very same doomsters are seen off. GEX celebrated its ongoing fundamental improvement, with news regarding its key Mt Winter EPA 155 Setting/Seismic. The shares were up 37.8% on the week.
This week I had decent conversations regarding a couple of companies. The first was Anglesey Mining (AYM) , a company whose reboot is already well underway. It is also a company which is via new management, moving to be a serious player in terms of building up significant home-grown assets. As the company which is “advancing the UK's largest polymetallic Volcanic Massive Sulphide ("VMS") project at the 100% owned Parys Mountain Cu-Zn-Pb-Ag-Au VMS deposit in North Wales, announced last month the receipt of results for the exploratory geospatial analysis project from Satellite Applications Catapult and the British Geological Survey. It may be the case that as far as AYM is concerned, Anglesey could be the new Cornwall.
The AIM market has not exactly been on fire in the recent past, something which has been underlined by the ongoing exodus from the formerly star exchange. However, the tide may be turning, if only in the form of Roundhouse AI (RHAI), which is moving from Aquis to AIM on Tuesday 13th October. The company is looking to be the Bloomberg in terms of ensuring AI agents can interact successfully in a trust-based environment. Given the size of the addressable market – trillions, the initial £14m market cap is as cheap as chips, and the £1.5m raise rather modest. The IPO price is 5p, but if the company even gets a tiny niche in its chose space broker Clear Capital’s 40p 12 month price target can be regarded as frugal. Above all, it would be great to see a UK listed mega tech winner. We have not had our fair share.
https://drive.google.com/file/d/1U5zOQazg2ppDLghDL9c-48VkIdBZ55Rr/preview