Hannam & Partners has reiterated its risked net asset value (NAV) estimate of 16.4p per share for Prospex Energy (PXEN) , implying ~170% upside from the share price of 6.1p, following a strong third-quarter performance driven by record revenue from the Selva gas field in Italy.
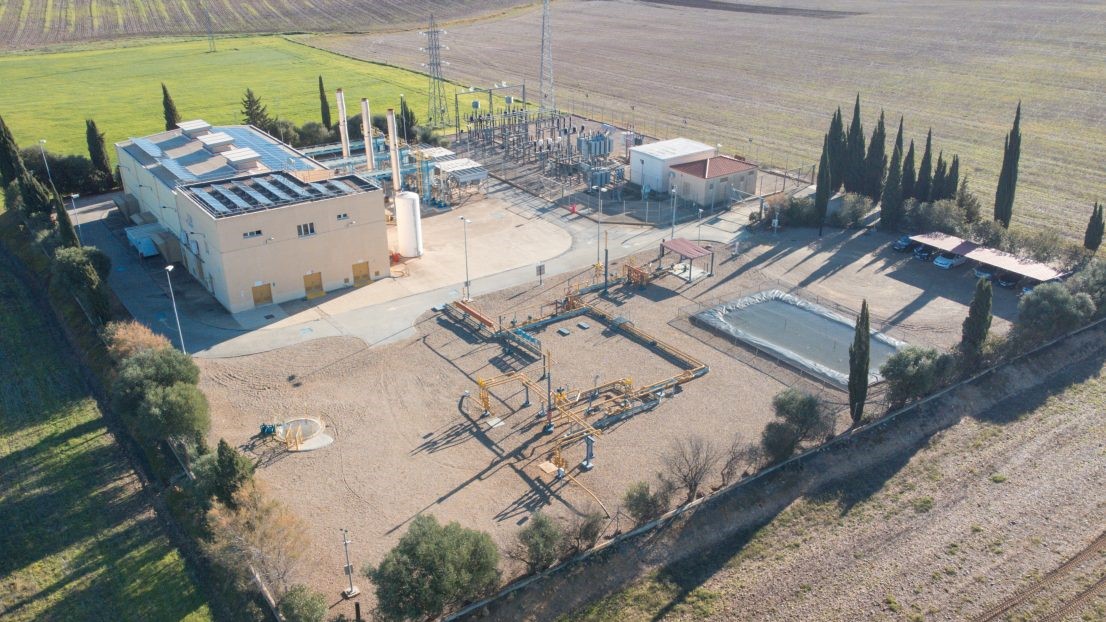
The broker highlighted a 41% quarter-on-quarter increase in group cash receipts to £1.7 million, taking year-to-date receipts to £3.8 million, already exceeding the full-year 2025 total. Selva generated record net revenue of ~£1.5 million, up 35%, supported by realised gas prices of ~US$23 per thousand cubic feet, a 44% increase over the previous quarter.
Hannam noted that stronger gas prices more than offset a modest decline in Selva production, while October prices above US$26 per thousand cubic feet should support fourth-quarter revenue despite temporary production constraints.
Elsewhere, El Romeral generated a positive net cash contribution of £105,000 during the quarter, while the installation of a permanent transformer is expected to reduce monthly operating costs by ~£12,000. At Viura, initial results from water reinjection testing have been encouraging, potentially improving gas recovery and supporting future development.
Looking ahead, the broker identified several catalysts, including the planned farm-out of Prospex's Polish assets, progress towards environmental approval for four new Selva wells and the interpretation of 3D seismic data ahead of the proposed 2027 drilling campaign.
Hannam estimates that Prospex could increase production eightfold by 2028 through the development of existing reserves, resources and exploration prospects.
View from Vox
Hannam's unchanged 16.4p risked NAV highlights the potential valuation upside from Prospex's existing producing assets and development portfolio. Strong European gas prices are supporting cash generation, while progress on Selva drilling approvals and securing development partners in Poland could provide important catalysts for unlocking further value.