Hannam & Partners has maintained its 16.4p per share risked net asset value for Prospex Energy (PXEN) following a site visit to the company’s Dunajec licence in southern Poland, with the broker describing Poland as a potentially material value driver.
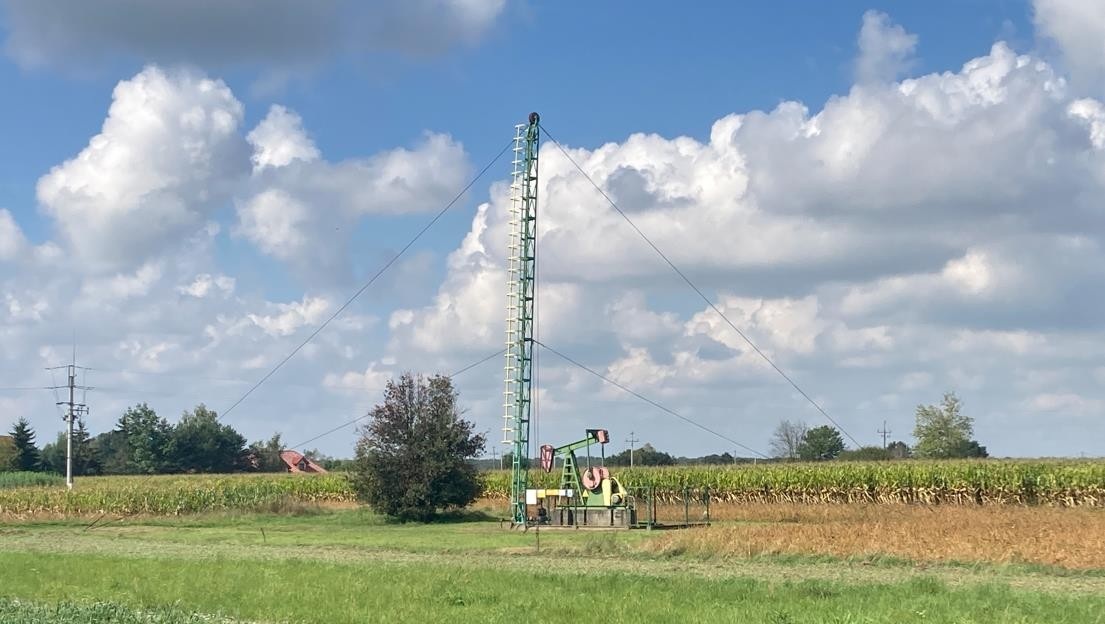
H&P visited the Dunajec licence with Prospex’s management and technical team in September, including the mapped Mniszów field, candidate pilot well locations and active wells on the neighbouring Grobla field. The broker said Prospex has moved from analysing raw legacy data following the licence award in April to an executable development plan in less than six months.
Prospex has revised its Mniszów development plan following a review of historic data, analogue field performance and input from service providers. The company has moved from a plan based on ~15 vertical wells to eight horizontal wells, while continuing to target ~3.7 million barrels of recoverable oil.
H&P assumes each lateral well could initially produce ~300 barrels per day and recover up to 450,000 barrels. The broker said horizontal drilling should allow the wells to intersect more of the natural fracture network within the reservoir than the historic vertical wells.
The planned programme starts with ~37 line kilometres of 2D seismic in Q1 2027 to confirm reservoir continuity, depth and thickness and map major faults. The Mniszów X-1 pilot well is then targeted for Q4 2027, comprising a vertical section followed by an open hole lateral of ~400 metres or longer.
If the pilot is successful, Prospex plans a four-well programme in late 2028 followed by three to five infill wells from 2029, with H&P’s base case assuming three. The phased programme is intended to allow cash generated from earlier wells to contribute towards later development.
Elsewhere, H&P noted progress across Prospex’s wider portfolio. A decision on the Selva environmental impact assessment is expected around year end ahead of a planned four well programme in 2027, while El Romeral is dispatching electricity during higher priced peak hours and Viura is preparing an injectivity test aimed at reducing water disposal costs.
H&P’s overall risked NAV remains 16.4p per share, comprising 7.9p from 2P and 2C reserves and resources and 8.4p from exploration.
View from Vox
H&P’s site visit gives the broker greater detail on Prospex’s Polish development plans, with the revised horizontal well programme offering potentially stronger early production from fewer wells. Near term catalysts include a potential farm down partner, the preliminary estimates and 2D seismic ahead of the planned Q4 2027 pilot well.